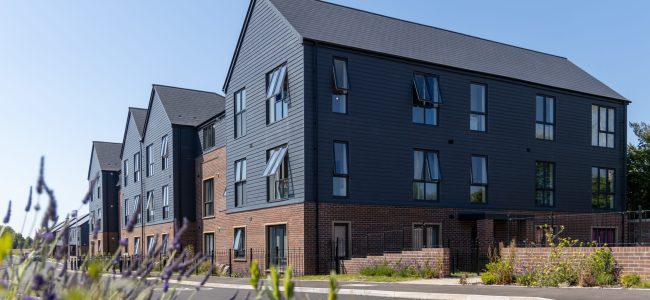

Registered social landlords in Wales have been invited to apply for development finance under a new Welsh Government loan scheme for 2026–27, as pressure continues to increase the supply of affordable homes.
The Welsh Government has approved the opening of the Registered Social Landlord Development Loan Scheme for applications during the current financial year.
Registered social landlords, commonly known as housing associations, are important providers of affordable and social housing across Wales.
Unlike private developers, they generally operate on a not-for-profit basis, reinvesting income in homes, services and further development.
The availability of finance is a central factor in determining how quickly new housing schemes can proceed.
Why housing associations need development finance
Building new homes requires substantial expenditure before properties are completed and rental income begins.
Housing associations must acquire land, secure planning permission, commission surveys, pay contractors and meet building standards.
Projects can become difficult to finance when construction costs rise or borrowing becomes more expensive.
Development loans can help organisations manage these pressures by providing access to capital during the construction process.
However, the detailed terms of the new Welsh scheme have not been established from the published decision summary.
It is not yet clear what interest rates will apply, how long loans will run or whether particular types of development will receive priority.
Could the scheme increase affordable housing delivery?
Additional development finance could help housing associations progress projects that might otherwise be delayed.
But the availability of loans does not automatically result in more homes being built.
Delivery also depends on planning permission, suitable land, contractor capacity, construction costs and the availability of other funding.
Housing associations may require a combination of borrowing, grant support and rental income to make individual schemes financially viable.
The impact of the programme will therefore depend on whether its lending terms make projects more achievable.
Public accountability
Development loans differ from grants because the expectation is generally that borrowed money will be repaid.
Nevertheless, public lending still requires scrutiny.
Important questions include the amount of money available, how financial risks will be managed, the criteria used to approve applications and the number of homes expected to result.
There is also a need to distinguish homes that would have been built anyway from additional homes made possible by the scheme.
Why it matters
Wales needs a sustained supply of affordable housing, particularly in communities where private rents and house prices are beyond the reach of many households.
The new loan scheme could help housing associations overcome financial barriers to development.
However, its contribution cannot yet be quantified.
The key information still required is the scheme’s total lending capacity, loan conditions, expected number of homes and the timetable for delivery.